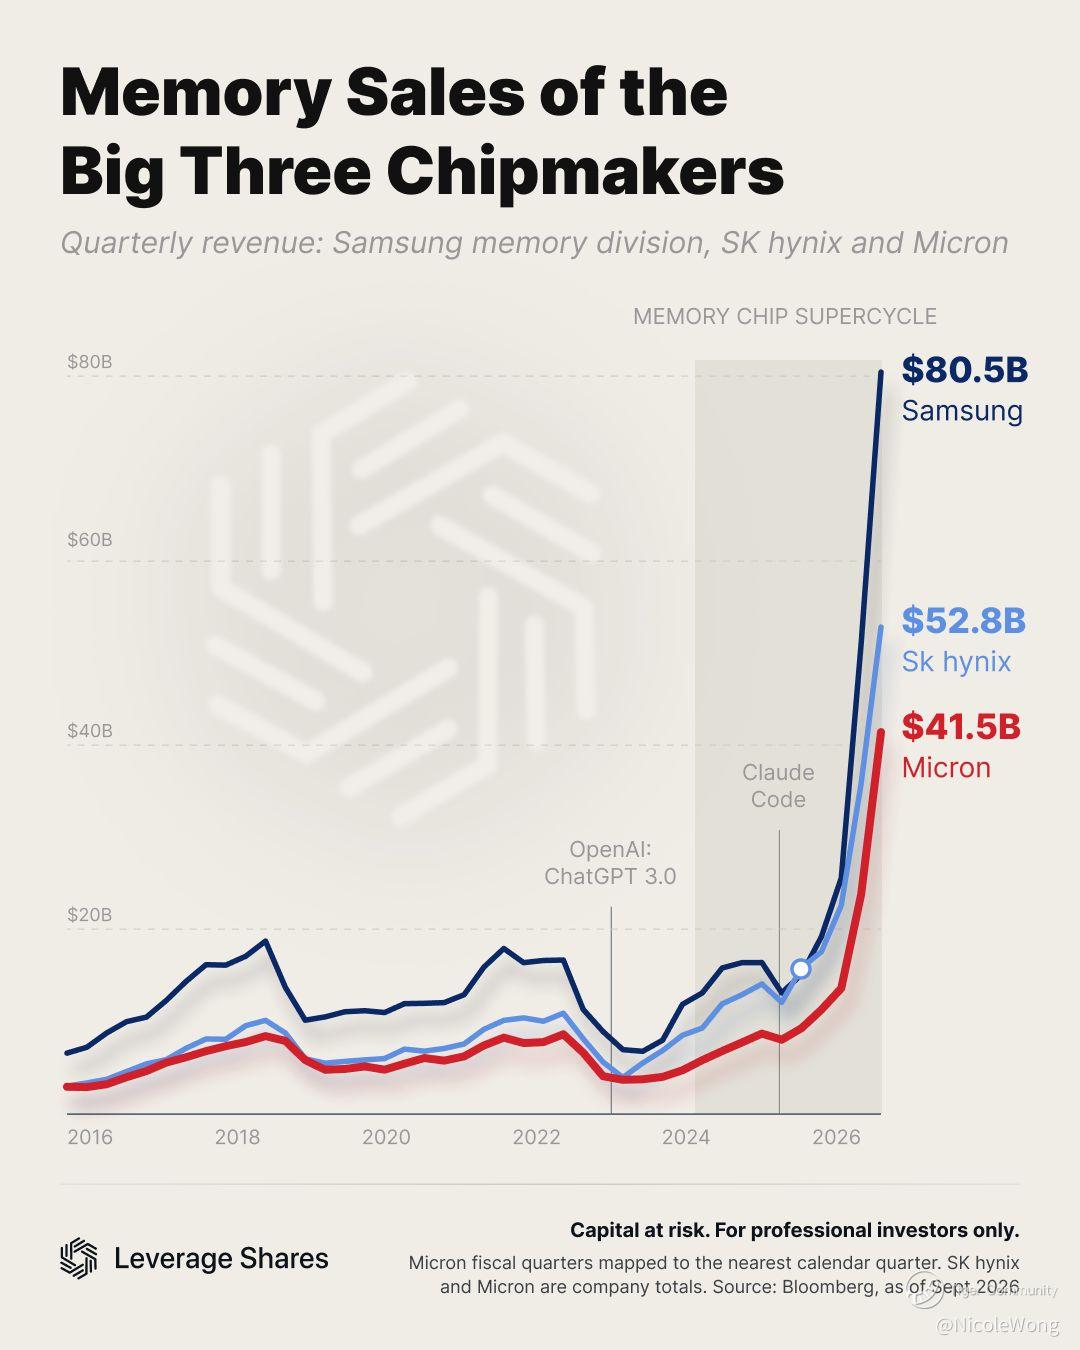
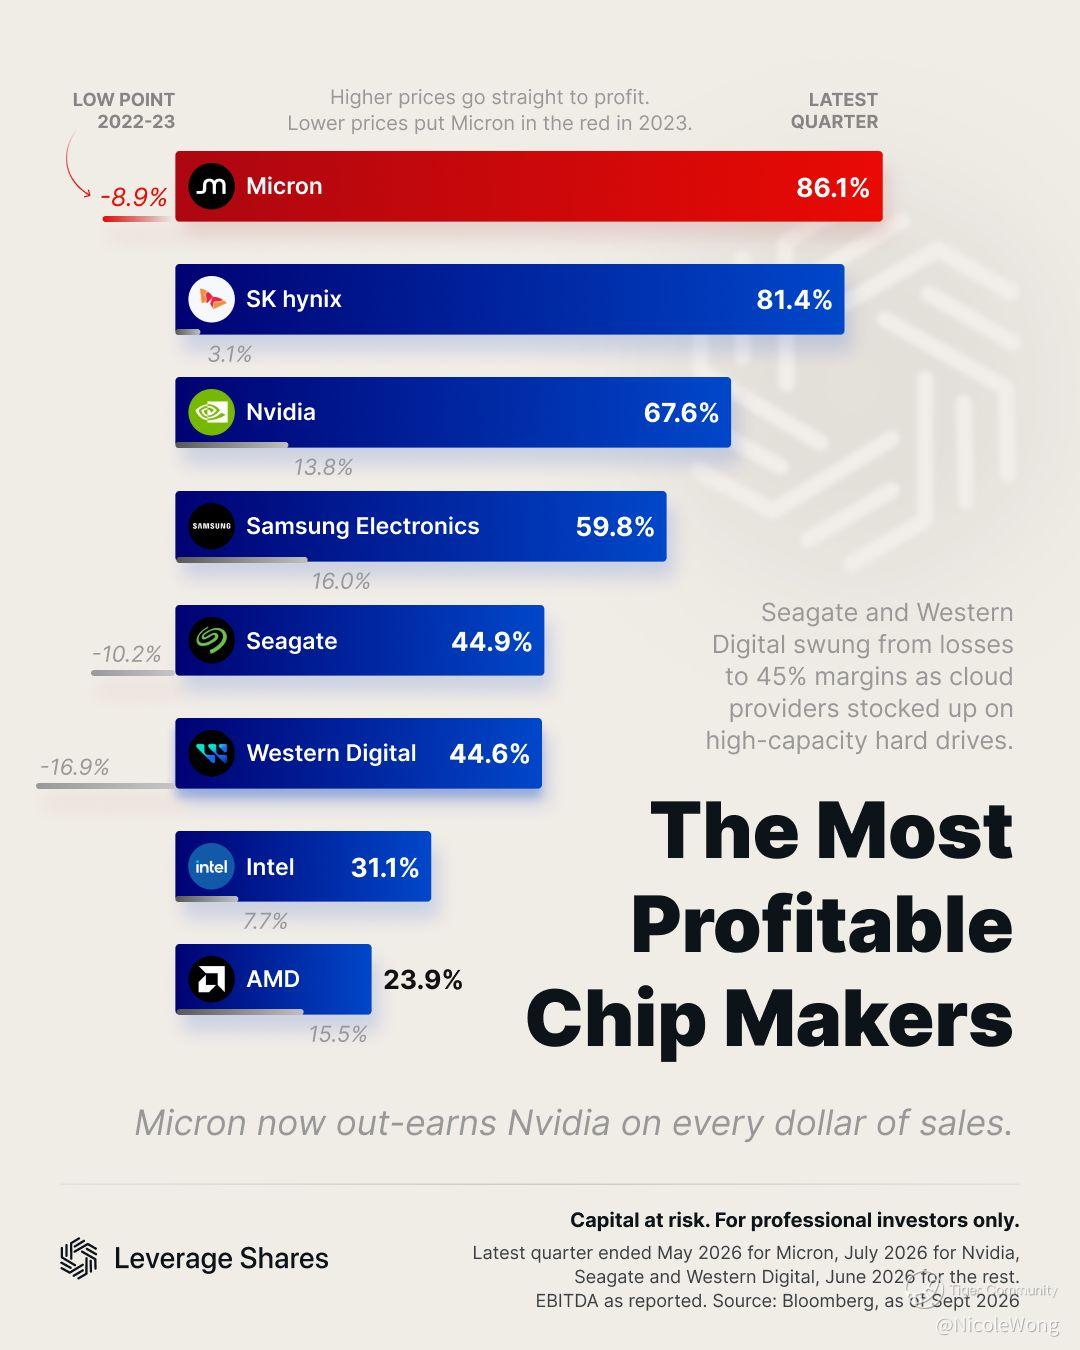
The memory chip supercycle, in two charts.
Memory has long been treated as the commodity end of the semiconductor industry. The latest numbers suggest that's changing.
📈 Revenue: In the latest quarter, Samsung's memory division booked $80.5B in sales, SK hynix
$SK海力士(SKHY)$ $52.8B and Micron
$美光科技(MU)$ $41.5B. All three are well above any level since 2016.
💰 Margins: Micron's EBITDA margin went from –8.9% at its 2022–23 low to 86.1% in its latest quarter. That puts it ahead of Nvidia
$英偉達(NVDA)$ at 67.6%, with SK hynix at 81.4%.
In memory, higher prices go almost straight to the bottom line. That works in both directions, and right now it's working in the sector's favour.
Disclaimer: Investing carries risk. This is not financial advice. The above content should not be regarded as an offer, recommendation, or solicitation on acquiring or disposing of any financial products, any associated discussions, comments, or posts by author or other users should not be considered as such either. It is solely for general information purpose only, which does not consider your own investment objectives, financial situations or needs. TTM assumes no responsibility or warranty for the accuracy and completeness of the information, investors should do their own research and may seek professional advice before investing.
Comments